Author: Nick Little, Principal Financial Adviser at Professional Private Wealth
Government Bonds 101: The IOU With A Very Reliable Borrower
Nick Little - October 2, 2026
What happens when you lend money to the Australian Government?
Government Bonds rarely make headlines, but they can provide regular income and help steady a portfolio. Here’s how they work, and the one thing that surprises most people about them.
Government Bonds 101: The IOU With A Very Reliable Borrower
Imagine the Government knocks on your door and asks to borrow $10,000.
It promises to pay you interest twice a year and give your $10,000 back on a set date. Sounds like a fair deal from a dependable borrower.
That’s essentially a Government Bond.
When you buy a bond, you’re lending money. In return, you receive regular interest payments, called coupons, and get the bond’s face value back when it matures. As an example, Australian Government Treasury Bonds pay a fixed rate of interest for the life of the bond, paid every six months.
The Part That Surprises People
Most people assume a Government Bond can’t fall in value. It can, because of interest rates.
Say you own a $100 bond paying 3%. Then interest rates rise, and new bonds start paying 5%.
If you want to sell your 3% bond, nobody will pay the full $100 when they could buy a new one paying the higher rate of 5%. The price of your bond has to fall to attract a buyer.
When interest rates rise, the value of existing bonds usually falls. When rates fall, it usually rises. The good news: if you hold the bond until it matures, you get back its face value. If you sell before then, you get whatever the market will pay, which may be less.
So Why Own Them?
Think of a portfolio like a football team.
Shares and property are your forwards. They’re exciting and they kick the goals, but they can have wild days. Bonds are your defenders. They don’t often make the highlights, but they help the team hold its shape when things get messy.
Bonds are a defensive asset: generally lower risk and less volatile than shares and property, while still offering a steady income and diversification.
That matters most when you start drawing on your savings. At 35, a bad year on the share market is annoying. At 70, when you’re living off your portfolio, it can feel very different. Defensive assets can help give growth assets time to recover without you being forced to sell them at the wrong moment.
How Do Returns From Bonds Compare To Cash And Deposits?
Many of us want to pass on more than wealth.
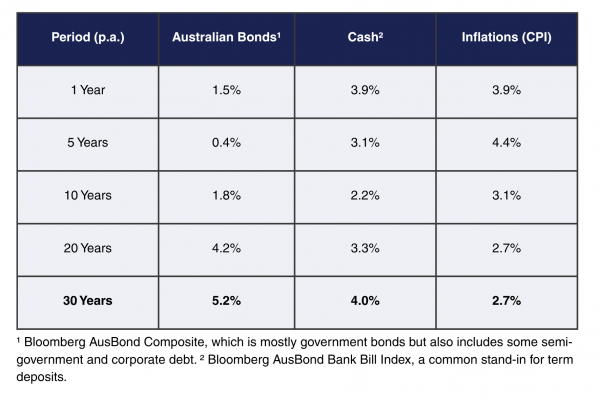
Over 20–30 years, Australian Bonds have beaten cash returns, but over the past 5–10 years cash has come out ahead, due to the lower interest rate / rising interest rate environment over this period. According to Vanguard Research, the returns to 30 June 2026 have been:
Nick’s Take
Not every investment needs to be exciting. Some just need to do their job.
Government Bonds won’t get people talking at a barbecue. But they can provide steady income, help you sleep better when share markets are rough, and give your growth assets time to do their work.
Just remember that “defensive” doesn’t mean “never falls in value.” When interest rates move, bond prices move too. However, if you hold quality Government Bonds until maturity, you will receive your investment back.
The question isn’t whether bonds are a good investment. It’s what job they’re doing in your portfolio.
Curious how the defensive side of your portfolio is set up, and why? Get in touch with Professional Private Wealth on 0408 702 056 or click below.
IMPORTANT INFORMATION
The information provided in this communication is general in nature only and does not constitute personal financial advice. The information has been prepared without taking into account your personal objectives, financial situation or needs. Before acting on any information in this communication you should consider the appropriateness of the information having regard to your objectives, financial situation and needs.
This communication may contain certain ‘forward looking’ statements. Forward looking statements, opinions and estimates provided are based on assumptions and contingencies which are subject to change without notice, as are statements about market and industry trends, which are based on interpretations of current market conditions. Forward-looking statements including projections, indications or guidance on future earnings or financial position and estimates are provided as a general guide only and should not be relied upon as an indication or guarantee of future performance. There can be no assurance that actual outcomes will not differ materially from these statements.
OTHER POSTS
Smart Strategy: Give The Kids A 50% Head Start
When teenagers get a part-time job, the Government may help build their super.
A little-known Government scheme can add up to $500 to a young worker’s super. Started early enough, that head start could grow into tens of thousands of dollars by retirement.

Is AI Today’s Steam Engine?
Billions are being poured into Artificial Intelligence infrastructure every month. Some economists believe future generations may look back on today’s AI boom the same way we look back on the early days of the Industrial Revolution.