Author: Nick Little, Principal Financial Adviser at Professional Private Wealth
Smart Strategy: Give The Kids A 50% Head Start
Nick Little - October 2, 2026
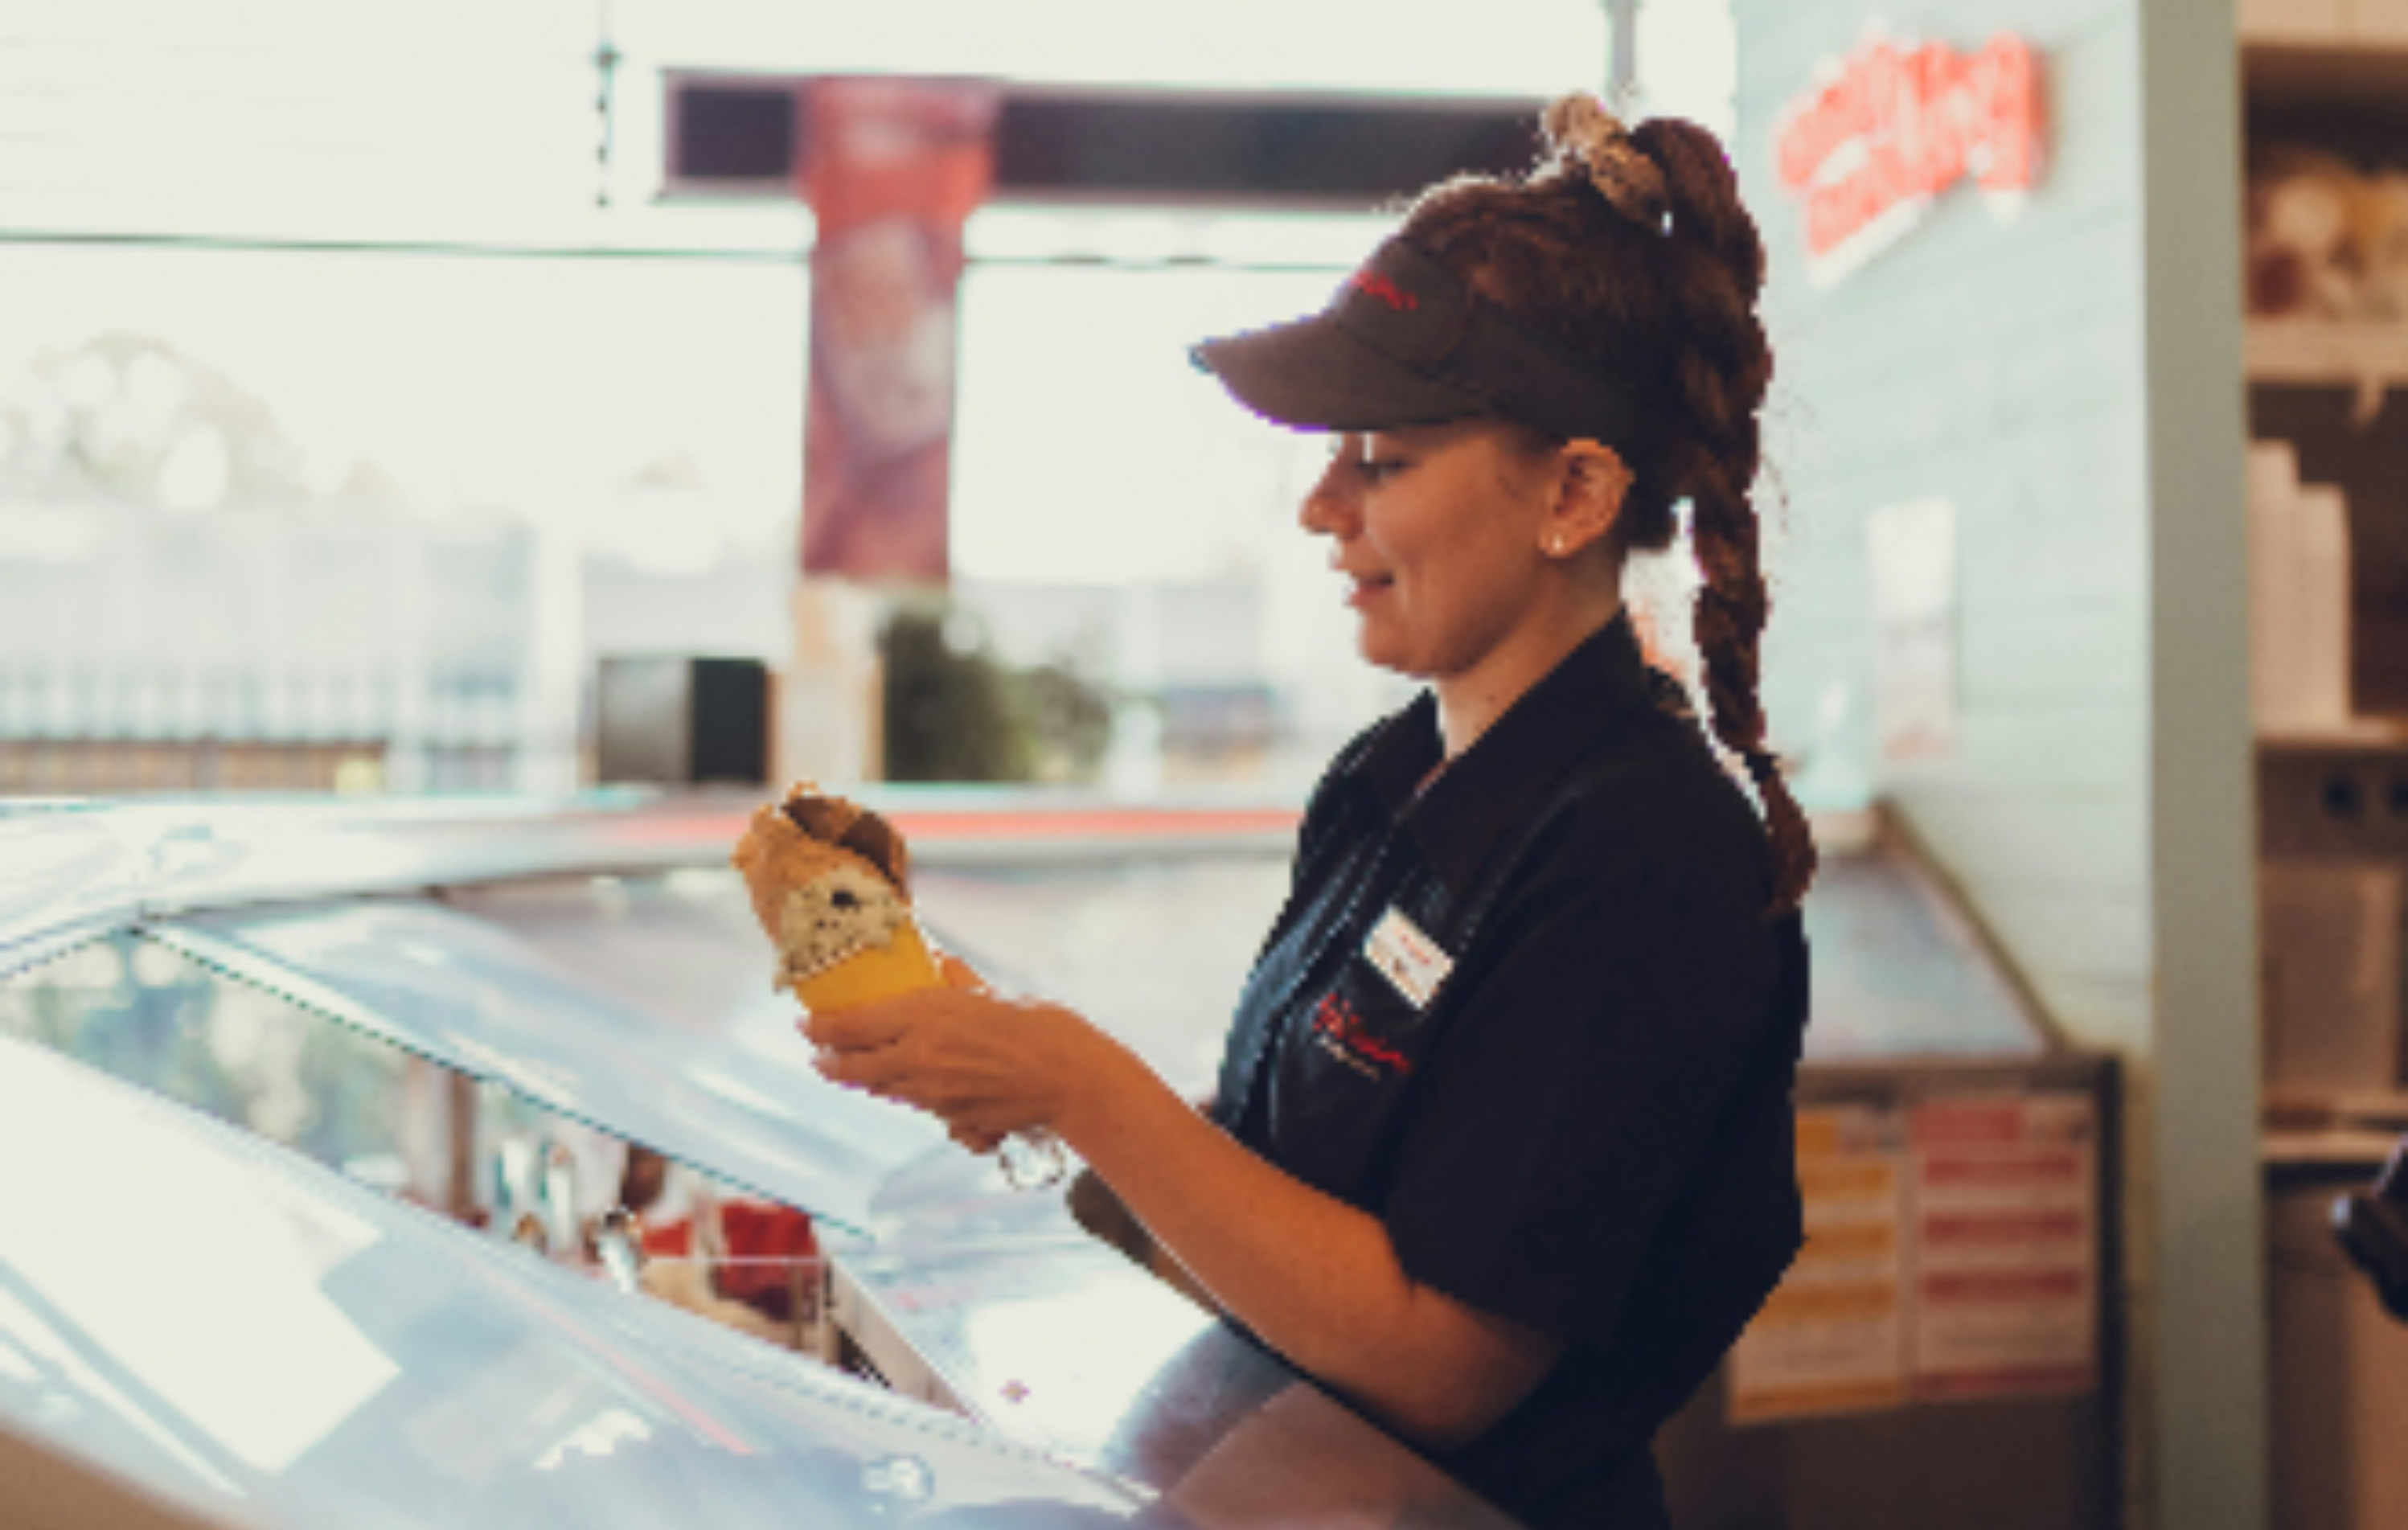
When teenagers get a part-time job, the Government may help build their super.
A little-known Government scheme can add up to $500 to a young worker’s super. Started early enough, that head start could grow into tens of thousands of dollars by retirement.
Smart Strategy: Give The Kids A 50% Head Start
Picture the typical teenager’s first pay cheque.
There are plenty of places it could go.
New clothes. A phone. Petrol. Food delivery. Something mysterious arriving from Amazon that apparently was absolutely essential. Superannuation probably isn’t high on the list.
But buried inside Australia’s super system is a little-known opportunity that can make those first years of working surprisingly valuable. It’s called the Government super co-contribution.
And for an eligible low or middle-income earner, the maths is pretty compelling.
Put $1,000 of after-tax money into super and the Government may contribute up to another $500.
How The Strategy Works
It uses the Government super co-contribution. If a low- or middle-income earner makes a personal after-tax contribution to super, the Government may add up to $500.
For 2026–27, anyone earning $49,293 or less who contributes $1,000 gets the full $500. The amount reduces as income rises and stops at $64,293. Most teenagers with a casual job sit comfortably below that.
The other key rule: at least 10% of their income must come from work. That’s why the “sweet spot” is usually from their first casual job (around age 15) until they start full-time work.
You don’t apply for it. As long as a child lodges a tax return and their super fund has their tax file number, the ATO pays the co-contribution automatically.
The First Home Bonus
Locking money away until 60 can feel a bit abstract for a teenager. This is where it gets clever.
Under the First Home Super Saver (FHSS) scheme, your child may later withdraw their own voluntary contributions, up to $50,000 in total, to help buy their first home. Contributions made before they turn 18 still count.
The Government’s co-contribution can’t be withdrawn. It stays in super, quietly compounding for retirement. That means one small habit can help with two big goals: a first home and a better retirement.
Before You Start
- Not every super fund accepts children. Anyone under 18 may need a parent to authorise their membership.
- They’ll need a tax file number and must lodge a tax return every year.
- Choose a low-fee fund. Fees can easily eat into small balances.
- They must be eligible. The ATO sets income, age and other requirements.
Nick’s Take
What I love about this strategy is how little it takes: around $19 a week, a tax return and the patience to let it grow.
Will teenagers thank you for it? Probably not. Not today, anyway. But their 60-year-old self might want to give you a very big hug.
And when they’re in their mid-20s, facing a home deposit, the Bank of Mum and Dad (or Nan and Pop) may not need to make quite such a big withdrawal. A plan started early can make that conversation a lot easier.
Have children or grandchildren who’ve just started working? Get in touch with Professional Private Wealth on 0408 702 056 or click below to see whether this strategy could suit your family.
IMPORTANT INFORMATION
The information provided in this communication is general in nature only and does not constitute personal financial advice. The information has been prepared without taking into account your personal objectives, financial situation or needs. Before acting on any information in this communication you should consider the appropriateness of the information having regard to your objectives, financial situation and needs.
This communication may contain certain ‘forward looking’ statements. Forward looking statements, opinions and estimates provided are based on assumptions and contingencies which are subject to change without notice, as are statements about market and industry trends, which are based on interpretations of current market conditions. Forward-looking statements including projections, indications or guidance on future earnings or financial position and estimates are provided as a general guide only and should not be relied upon as an indication or guarantee of future performance. There can be no assurance that actual outcomes will not differ materially from these statements.
OTHER POSTS
Why Is Everyone Still Talking About Inflation?
Just when it looked like inflation was coming under control, it came roaring back into the conversation.
There isn’t one simple reason. Government spending, strong demand, supply-side shocks, global conflicts, the AI investment boom and Australia’s housing shortage are all playing a role, and understanding this mix helps explain why interest rates remain such a big issue.
Getting More Bang for Your Buck with the Bank
When did you last check what your bank is actually paying you, or charging you?
With interest rates now much higher, a small difference in the rate on a sizeable deposit or loan can translate into thousands of dollars a year. Sometimes all it takes to improve it is knowing what you’re getting and asking the bank a very simple question.